A startup can grow fast, attract eager customers, and still destroy value with every new sale. Revenue growth, a large market, and a compelling product can all create the appearance of momentum without answering the one question that actually matters: does the business generate more economic value from each customer, order, or subscription than it spends acquiring and serving that unit?
That is the entire premise of unit economics.
Investable unit economics do not require a startup to already be profitable — early-stage companies routinely invest ahead of revenue and accept temporary inefficiency while they test a market. What makes the model investable is evidence that each incremental unit can eventually produce attractive contribution, that the path to profitability is measurable, and that growth strengthens rather than weakens the company's financial position.
Unit Economics Is a Business Model Test
At its simplest, unit economics isolates the revenue and direct costs tied to a single unit of business — one customer, one subscription, one order, one loan, one marketplace transaction. The right unit depends entirely on how value is created: a subscription company may use the account as its core unit, a marketplace must examine both sides of the transaction, a lender may need to evaluate the loan itself. Choosing the wrong unit produces a misleading picture — a marketplace can report attractive customer-level revenue while losing money on every transaction once fulfilment, payments, and incentives are properly allocated.
The discipline starts with definition: what exactly is being measured, why it represents the core economic exchange, which revenue and costs attach to it, and how it behaves over time. That definition should stay consistent across management reporting, board materials, and investor diligence — a unit that changes whenever the economics look unfavorable quickly erodes confidence in the whole analysis.
Revenue Quality Comes First
Not all revenue carries the same economic value. A credible model separates recurring from non-recurring revenue, contract value from recognized revenue, and initial revenue from expansion revenue. Recurring-revenue metrics are only meaningful when they represent genuinely ongoing, contracted revenue rather than one-time implementation fees or pilots (Sacks, 2021).
Timing matters just as much as classification: a customer may sign a contract today and generate revenue gradually over months, and treating bookings, billings, revenue, and cash collections as interchangeable obscures exactly where the business actually stands in its commercial cycle. The relevant question for unit economics is never how much revenue has been booked — it is how much of that revenue is genuinely repeatable, and when it converts into gross profit and cash.
Contribution Margin Is the Core
Revenue alone does not make a unit attractive; the first real profitability layer is contribution margin — revenue per unit minus the variable costs that rise as the business delivers more of it, including hosting, payment processing, fulfilment, support, and usage-based infrastructure.
Gross margin typically subtracts cost of goods sold; contribution margin goes further by including variable operating costs directly tied to serving the customer, which is why a company can report a healthy gross margin while producing weak contribution if every account demands heavy onboarding or support (CRV, 2026).
Consider a subscription company charging a flat monthly fee, where infrastructure, data, payment processing, and support together consume a meaningful share of that revenue, leaving a contribution margin in the 50–60% range. If that same company spends a large multiple of one month's contribution to acquire the customer, it may need well over a year of contribution before recovering its acquisition cost — and if the customer churns before that point, the relationship destroys value even though it generated positive monthly contribution the entire time. This is precisely why unit economics require contribution, retention, and payback to be read together rather than in isolation.
CAC Must Be Fully Loaded
Customer acquisition cost is sales and marketing spend divided by new customers acquired — a simple formula that is only useful when both sides are defined carefully. Investors routinely challenge “thin” CAC calculations that exclude sales salaries, marketing tools, or onboarding resources required to actually win and activate a customer, since understated CAC makes a business look more efficient than it is (CRV, 2026).
The denominator deserves equal scrutiny: dividing spend by every new account created, including free users and trials, produces a misleadingly low number. Timing complicates it further — a long enterprise sales cycle means today's spend may not convert into a customer for several quarters, which is why CAC analysis sometimes uses a prior period's spend against current acquisitions to reflect how the sales process actually works (Sacks, 2021).
The most useful CAC is never a single blended figure; it is segmented by channel, customer size, geography, and sales motion, since an attractive blended number often just means organic referrals are diluting the real cost of paid growth.
LTV Is a Forecast, Not a Fact
Lifetime value estimates the gross profit a customer generates over the relationship — and it is one of the easiest startup metrics to overstate.
LTV should be built on gross margin rather than raw revenue, since revenue overstates customer value whenever the business incurs material cost to serve it (CRV, 2026). A model that assumes every customer stays active indefinitely, or that applies today's low churn rate to a customer base observed for only a year, can produce an LTV that looks impressive and is structurally fragile: a very low monthly churn rate implies an average customer lifetime stretching many years, which is rarely a safe assumption for an early-stage product.
LTV is more credible presented as a range — base, downside, and upside cases grounded in the retention curve actually observed — than as one precise, unquestionable number (CRV, 2026). The right question is never “what is the highest plausible LTV,” but what level of lifetime gross profit is genuinely supported by observed customer behavior, and how sensitive that number is to the retention assumption underneath it.
Retention Reveals Whether Value Persists
Acquisition only begins a customer relationship; retention determines whether it creates durable value. This is why investors look at retention through cohorts rather than a single aggregate churn figure — grouping customers by their first billing period and tracking revenue behavior over time (OpenView, 2010a).
Cohort analysis can reveal whether newer customers retain better than earlier ones, whether churn concentrates in a specific segment, and whether the business is quietly acquiring lower-quality customers as it scales; a sharp revenue decline in the second month across multiple cohorts, for instance, often signals weak onboarding well before it shows up in a company-wide number (OpenView, 2010b).
Logo retention and revenue retention tell different stories and should be read together. Net revenue retention captures beginning revenue less churn and contraction, plus expansion, and can exceed 100% when expansion outpaces losses — meaning an existing cohort grows in value even without a single new sale.
David Sacks describes net revenue retention below 100% as a “leaky bucket”: new sales pour in while churn and contraction quietly drain the base beneath them (Sacks, 2021). A business can retain most of its logos while failing to grow account value, or lose many small customers while expanding substantially within a smaller set of large ones — neither metric alone tells the full story.
LTV:CAC Is Useful but Incomplete
The LTV:CAC ratio compresses several questions into one number: does acquisition produce a surplus, and is that surplus large enough to matter? A 3:1 ratio is a common reference point, though CRV notes investors rarely apply it mechanically — a lower ratio that is visibly improving can be more attractive than a higher one that is flat or declining (Aspire, 2026; CRV, 2026).
The ratio misleads when LTV is built on revenue instead of gross profit, when churn rests on an immature sample, when CAC quietly excludes real costs, or when the number blends fundamentally different acquisition channels into one average. A company with a strong ratio and a very long payback period may be less investable than one with a modest ratio and a short payback, depending on the company's stage and access to capital — the trajectory of the number, and why it is moving, usually matters more than the number itself.
Payback Connects Economics to Cash
CAC payback measures how long it takes to recover acquisition cost through gross profit or contribution margin, and it is fundamentally a cash-timing metric — two companies with similar lifetime economics can have very different funding needs depending on how quickly each recovers its acquisition spend. A long payback period means the company must finance growth for longer, becomes more sensitive to swings in conversion and margin, and risks losing customers to churn before ever recovering what it spent to win them.
Payback should be judged against the sales model in question — a self-serve product and an enterprise field-sales motion can reasonably carry different payback periods given how differently they generate contract value and expansion (CRV, 2026) — and it should always be read alongside retention, since a short payback followed by fast churn is not actually healthy, while a longer enterprise payback can be entirely defensible when renewal and expansion are strong.
Growth Must Be Economically Constrained
Startups are routinely told to grow fast, but growth manufactured through heavy discounting, subsidized fulfilment, or premature sales hiring is not automatically valuable — it must show up as controlled marginal cost and stable or improving contribution, not just a rising top line.
For SaaS specifically, sales efficiency can be examined through the Magic Number — net new annual recurring revenue divided by the prior period's sales and marketing spend — with a value above one indicating reasonably efficient growth in the framework Sacks describes (Sacks, 2021), though the right threshold still depends heavily on sales-cycle length, contract size, and gross margin.
Burn multiple extends this logic to the company level: net burn divided by net new annual recurring revenue, showing how much cash the business consumes to generate each incremental unit of recurring revenue, with a lower multiple reflecting more efficient growth (Sacks, 2021). It can expose weaknesses invisible in CAC alone — a company can report low CAC and still burn heavily because of bloated implementation teams or high working-capital needs. Investable growth is not growth at any cost; it is growth that moves the company measurably closer to durable cash generation.
The Business Model Changes the Standard
There is no single definition of good unit economics — the right benchmark depends entirely on the business model:
Product-led businesses often show an attractively low CAC because the product itself does much of the acquisition work, but that number can mask real cost sitting in product and engineering budgets — net new ARR relative to cash burned is a useful supplement (CRV, 2026).
Enterprise sales-led businesses carry higher CAC and longer payback almost by design; that is acceptable only when contracts are durable, margins are strong, and expansion is actually observed, not assumed.
Marketplaces must analyze both sides of the network, since gross transaction value can grow quickly while the platform loses money on every completed transaction once incentives and support are properly allocated.
Consumer and transactional businesses often lose money on a first order to win the customer, which is only investable when repeat purchase behavior is demonstrated across real cohorts rather than assumed.
AI-native businesses face structurally different serving costs, since inference and infrastructure spend can rise with usage; CRV notes these companies may start with lower gross margins than traditional software, making the trajectory of that margin — not just its current level — the metric that matters (CRV, 2026).
Segmentation Prevents False Confidence
Blended metrics can conceal enormous differences within a customer base. Consider a startup selling into two very different segments:
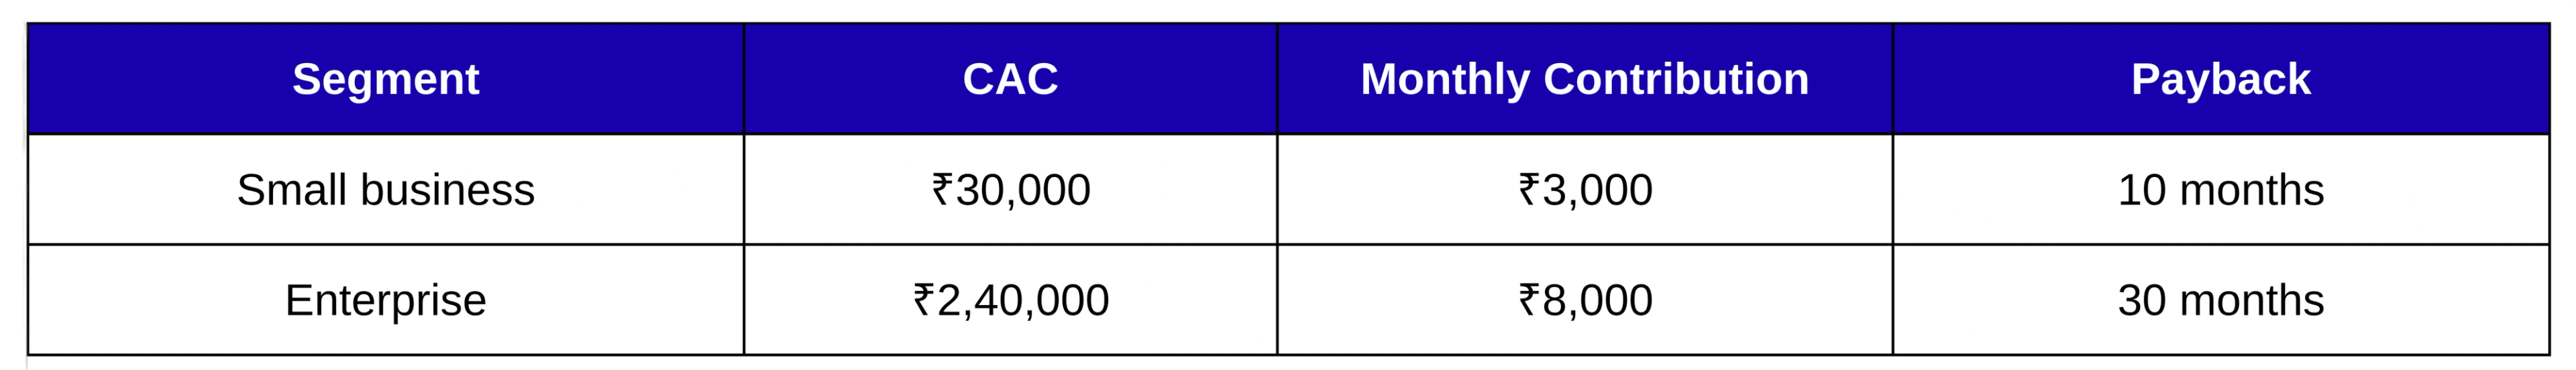
A single blended CAC and payback figure here would represent neither segment accurately. If enterprise customers retain and expand strongly, the longer payback may be entirely acceptable; if they instead require heavy servicing and churn unpredictably, it becomes a real problem.
CRV warns specifically that collapsing self-serve and enterprise channels into one blended CAC can destroy the analytical credibility of the whole model, since the two channels carry fundamentally different costs and conversion paths (CRV, 2026). Segmenting by channel, product, geography, and cohort is not just more rigorous reporting — it tells management which growth is actually worth buying.
Warning Signs Worth Deeper Diligence
Strong headline growth paired with weak retention, which cohort analysis will surface long before an aggregate churn number does.
A high LTV built on only a few months of customer history, which is closer to a theoretical projection than an empirical result.
A CAC figure that quietly excludes sales salaries or commissions, understating the real cost of growth.
LTV calculated on revenue instead of gross or contribution profit, which overstates customer value once delivery costs are material (CRV, 2026).
Blended metrics that combine incompatible segments — self-serve and enterprise, domestic and international — into one operationally meaningless average.
Heavy reliance on a small number of large customers, a concentration risk that deserves careful separate assessment regardless of how strong the blended ratios look (Sacks, 2021).
Metrics in a pitch deck that the finance team cannot reproduce from source data — a credibility problem, not a presentation one.
Why Unit Economics Shape Valuation
Two startups with identical revenue can deserve very different valuations once retention, margin, capital intensity, and customer concentration are taken into account — a revenue multiple means very little without understanding the economics that produced that revenue.
The same logic extends directly into M&A: a buyer examining a target's cohorts, acquisition channels, and support burden is really asking whether the customer base is economically attractive at the account level, whether retention survives a change of ownership, and whether the acquisition engine can actually scale under new ownership. Unit economics, in that sense, are never just a fundraising metric — they are a foundation for strategic valuation and transaction diligence more broadly.
The Standard Is Not Perfection
Early-stage startups rarely have fully mature unit economics, and requiring that kind of precision too early can discourage the experimentation that produces a real business model. The relevant standard is learning velocity and direction, not perfection: a company can be genuinely investable with temporarily depressed margins, a still-high but visibly improving CAC, or an LTV expressed as a range rather than a point estimate.
What matters is whether the company understands the gap between its current economics and its target economics, can name the specific levers that close that gap, and has real evidence that those levers are working. A weak business hides its assumptions behind falsely precise numbers; a strong one makes those assumptions visible, tests them against cohorts, and allocates capital accordingly.
A startup's unit economics become investable the moment growth starts to look like a repeatable economic process rather than a spending program. The essential questions stay the same regardless of business model: what is the unit, what does it cost to acquire and serve, how long does it stay active, does it expand, and how quickly is the acquisition investment actually recovered.
The strongest startups never rely on one attractive ratio — they show alignment across acquisition cost, contribution margin, retention, lifetime value, and cash consumption, measured by cohort and segment, with assumptions the team can explain rather than merely present.
Ultimately, investability comes down to one piece of evidence: that each additional unit makes the business stronger, and that this relationship keeps improving as the company learns, scales, and refines how it spends capital - a discipline Yajur Knowledge Solutions works with founders and dealmakers to build well before that evidence needs to hold up in front of an investor.
References
Aspire. (2026, January 9). What is unit economics, and what does it matter for your startup?
CRV. (2026, July 23). What Series A investors actually analyze in unit economics.
OpenView. (2010a, May 20). Revenue retention analysis: Creating the cohorts.
OpenView. (2010b, June 24). Revenue retention analysis: What to look for.
Sacks, D. (2021, October 18). The SaaS metrics that matter.